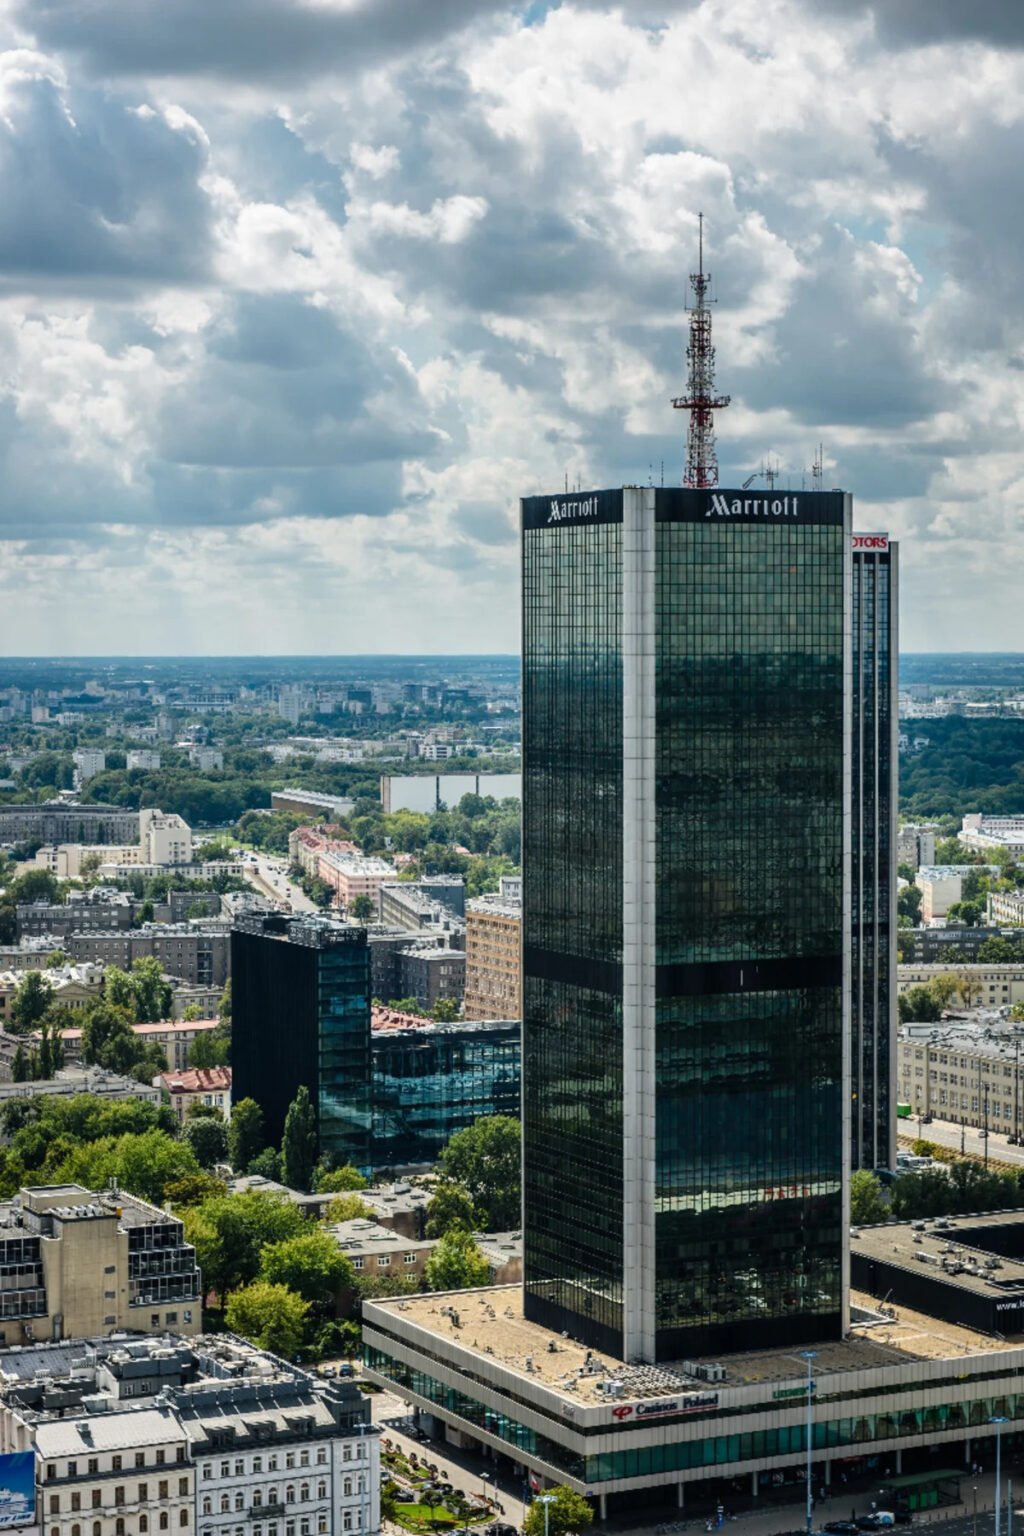
Marriott Worldwide, Inc. (NASDAQ:MAR)’s Center East enterprise confirmed a significant enchancment in July, with income per accessible room (RevPAR) declining 12% yr over yr, a pointy enchancment from the 43% decline within the second quarter. The development got here regardless of continued regional battle, suggesting that demand is proving extra resilient than initially feared. Extra importantly, Marriott’s international enterprise stays robust: international room income elevated 7% in July, with the U.S. and Canada up 8%.
Nevertheless, the Center East stays a danger to Marriott Worldwide, Inc. (NASDAQ:MAR)’s development technique. The area represents solely about 3% of Marriott’s international charges however 6% of its growth pipeline, that means extended battle can have an outsized affect on future lodge openings. Provide-chain disruptions and restricted capital flows have already delayed tasks, pushing Marriott towards the decrease finish of its full-year web unit development goal.
Marriott’s Center East Headwind Eases, however Struggle Dangers Stay
International Demand Offers a Cushion Towards Regional Weak spot
The most important optimistic is that the Center East headwind seems to be easing sooner than anticipated. Shifting from a 43% RevPAR decline within the second quarter to only 12% in July suggests journey demand can recuperate at the same time as geopolitical dangers stay elevated. If the battle stabilizes, Marriott Worldwide, Inc. (NASDAQ:MAR) may see a comparatively fast rebound in regional occupancy and room charges.
Extra importantly, the Center East is just not giant sufficient to overwhelm Marriott’s broader international efficiency. The corporate generated a 7% enhance in international room income in July, whereas U.S. and Canadian room income rose 8%. RevPAR development was additionally broad-based throughout luxurious, premium/choose and mid-scale manufacturers, suggesting that Marriott’s energy is just not dependent solely on rich vacationers.
Marriott additionally advantages from an asset-light, fee-driven mannequin, that means stronger lodge demand can translate into enticing money technology with out requiring the corporate to personal a lot of the underlying properties. Barron’s has highlighted the resilience of this mannequin, alongside the energy of Marriott Bonvoy and extra development alternatives from its credit-card partnerships.
The broader shopper shift towards spending on journey and experiences is one other structural tailwind. Marriott’s CEO argued that buyers throughout demographics proceed prioritizing experiences over bodily items, suggesting that journey demand may stay sturdy moderately than merely representing a short lived post-pandemic surge.
Renewed Battle May Reverse Marriott’s July Enchancment
The most important concern is that the Center East restoration may show untimely if the battle intensifies once more. The most recent escalation between the U.S. and Iran has already elevated uncertainty, whereas disruptions to business journey and regional tourism stay a serious menace. The Wall Avenue Journal experiences that Gulf tourism, aviation and lodges proceed to face important disruption, with Dubai lodge occupancy falling sharply throughout the first half of 2026.
Marriott Worldwide, Inc. (NASDAQ:MAR) additionally faces a longer-term growth drawback. As a result of the Center East represents 6% of its growth pipeline, extended supply-chain bottlenecks, financing disruptions and development delays may sluggish the addition of latest rooms. That’s notably necessary for Marriott as a result of unit development is a key part of its long-term payment development technique. Administration has already indicated that full-year web unit development is prone to are available towards the decrease finish of its goal.
Broader macroeconomic dangers additionally stay. Persistent battle has pushed oil costs larger and elevated inflationary stress, which may ultimately weaken shopper buying energy and discretionary journey spending globally. If the geopolitical shock turns into a protracted financial slowdown, Marriott Worldwide, Inc. (NASDAQ:MAR) may face weaker company journey, decrease leisure demand, and slower development past the Center East.
Conclusion
General, the information is extra optimistic than destructive for Marriott Worldwide, Inc. (NASDAQ:MAR), as a result of the Center East income decline is narrowing considerably whereas the corporate’s a lot bigger international enterprise continues to ship stable development. The July enchancment means that the regional drag could also be turning into manageable moderately than escalating.
That stated, the restoration shouldn’t be handled as a clear all-clear. The battle stays unpredictable, and Marriott’s publicity by means of its growth pipeline means extended instability may proceed delaying growth. For now, Marriott’s diversified international footprint, robust U.S. demand, and asset-light mannequin seem able to absorbing the Center East weak spot, making the story cautiously bullish until the geopolitical scenario deteriorates materially.
Whereas we acknowledge the potential of MAR as an funding, we consider sure AI shares provide larger upside potential and carry much less draw back danger. For those who’re searching for an especially undervalued AI inventory that additionally stands to learn considerably from Trump-era tariffs and the onshoring pattern, see our free report on thefinest short-term AI inventory.