Buyers keen to purchase into the futuristic imaginative and prescient of worthwhile driverless autos will get their likelihood quickly. Could Mobility is aiming to develop into the primary U.S. publicly listed pure-play possibility for an autonomous ride-hailing know-how firm. It’s poised to go public via a particular objective acquisition firm (SPAC), merging with ACP Holdings Acquisition (NASDAQ: ACGC) that values the mixed firm at roughly $1.4 billion.
It is anticipated to function as Could Mobility. buying and selling on the Nasdaq alternate beneath MAY. However earlier than traders get too excited, let’s pump the brakes and check out the small print.
Missed AI’s “Act 1”? Act 2 May Be 15x Greater. Most traders suppose they missed the AI boat as a result of they did not purchase Nvidia in 2005. However in accordance with our analysts, we’re solely on the finish of “Act 1″—the R&D section. “Act 2” is the worldwide rollout. Proceed »
Alternative knocks
It is simple for traders to get excited in regards to the alternative, however many won’t pay attention to the potential market dimension or development prospects. The worldwide robotaxi market is projected to succeed in about $415 billion by 2035, with the U.S. accounting for a roughly $48 billion slice of that pie. The fleet of U.S. industrial autonomous autos (AVs) is projected to broaden from solely about 4,000 autos presently to round 35,000 by 2030 — or about 8% of the ride-sharing market.
A yr in the past this month, Financial institution of America projected that the long-term U.S. complete addressable market (TAM) for AV ride-hailing is a trillion-dollar alternative as firms comparable to Could Mobility goal to exchange the drivers that take roughly 70% of each fare. It is also essential for traders to appreciate how early within the recreation that is: Alphabet‘s Waymo, with an estimated $350 million in annualized income, would characterize solely about 0.5% of U.S. ride-hailing bookings.
The chance is doubtlessly profitable, albeit nonetheless very early within the recreation. So, what makes Could Mobility intriguing?
An asset-light transition
Could Mobility is shifting to an asset-light mannequin. On the firm’s preliminary U.S. ride-hailing launch web site, it estimates the prices for the protection driver; autos (financing, depreciation, insurance coverage, upkeep); web site operations (gasoline/charging, depot operations, and employees); and distant automobile supervisors, software program upkeep, and discipline engineers. On this asset-heavy situation, Could Mobility’s projections put its annual income per automobile between $130,000 to $150,000, because it retains all of the income. However as a result of it additionally incurs all the prices, it checks in with a destructive gross margin per automobile with a security driver.
Below its asset-light mannequin, which incorporates eradicating the protection driver, Could Mobility transfers the automobile prices in addition to the location working prices to a fleet working companion, though it’s going to nonetheless incur the prices for distant supervisors, discipline engineers, and software program upkeep.
This situation would include a bigger fleet dimension because of a fleet-operator companion, and decrease income ($50,000 to $72,000 per automobile) because it splits the gross sales with that companion. However it checks in with a gross margin per automobile between $35,000 to $50,000 yearly as a result of it might push off important prices and will scale up extra rapidly while not having to buy and personal the fleet.
There’s additional upside with administration concentrating on a 50% discount in its invoice of supplies (BOM) by the top of 2028. That is from price financial savings realized via computing and sensors with next-generation chip alternate options and as lidar/radar/digicam markets scale up and mature.
Could Mobility additionally expects to cut back its BOM via price reductions in {hardware} parts and integration when its software program might be put in by the unique tools producer (with Toyota as a companion for AV-ready automobile platforms at scale) moderately than putting in it in autos afterwards. Over the long run with out drivers, administration is concentrating on gross margins of about 70%, and margins beneath earnings earlier than curiosity and taxes round 30%.
How going public helps
When the SPAC deal and merger closes, it might present Could Mobility with as much as $337 million in funding. Buyers can take a look at the economics and do the maths: In 2025, the corporate generated roughly $10 million in income with a 27% gross margin, whereas burning $93 million in money. The SPAC funds ought to allow it to strengthen its steadiness sheet and liquidity, finance added analysis and growth, put money into the availability chain to cut back prices, and launch new in markets with out drivers. Nevertheless, with out a main money pile, the money burn might erode its liquidity moderately rapidly.
What all of it means
It is an thrilling time in an automotive trade that is poised to evolve quickly over the following decade. Nevertheless, traders should perceive that that is an exceptionally high-risk funding presently. Could Mobility’s 27% gross margin is an encouraging starting, however the money burn is important and can solely enhance within the close to time period. It should rely closely on the $337 million of contemporary capital from its public debut, and that would erode quickly.
Buyers even have to contemplate that regardless of being within the early innings, there are some heavyweights accelerating ahead, together with market chief Waymo and Tesla‘s gradual however regular progress with its Cybercab enterprise.
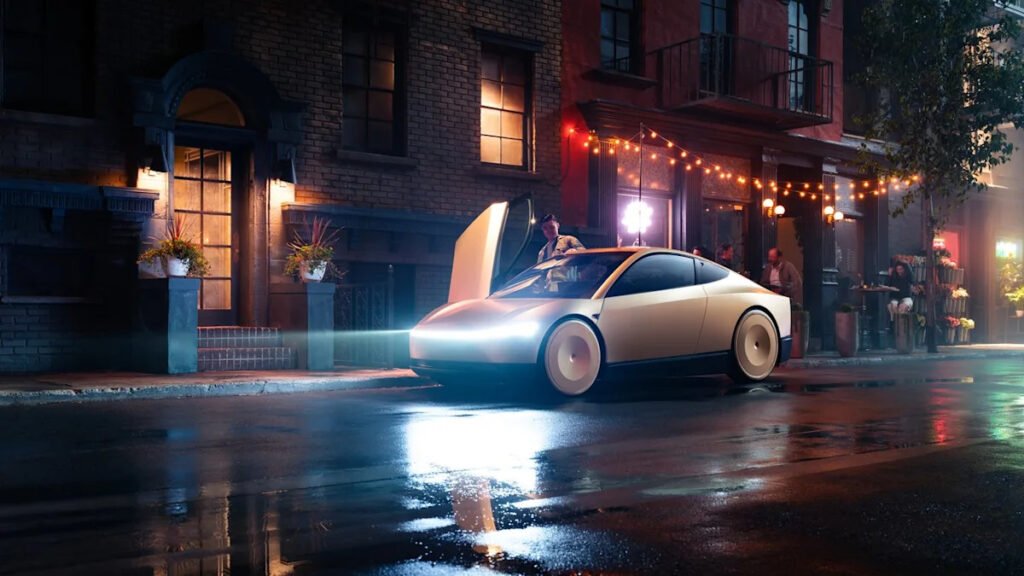
Tesla’s Cybercab. Picture supply: Tesla.
Could Mobility is intriguing, however this solely scratches the floor. Potential shareholders should learn via the investor presentation, accessible right here, and acknowledge that this might finish in a complete loss. For now, this needs to be an organization that the majority retail traders watch curiously from the sidelines, particularly as this debut assessments investor demand for a pure-play AV ride-hailing firm.
Must you purchase inventory in ACP Holdings Acquisition Corp. proper now?
Before you purchase inventory in ACP Holdings Acquisition Corp., think about this:
The Motley Idiot Inventory Advisor analyst staff simply recognized what they consider are the 10 finest shares for traders to purchase now… and ACP Holdings Acquisition Corp. wasn’t certainly one of them. The ten shares that made the reduce might produce monster returns within the coming years.
Take into account when Netflix made this checklist on December 17, 2004… for those who invested $1,000 on the time of our advice, you’d have $395,625!* Or when Nvidia made this checklist on April 15, 2005… for those who invested $1,000 on the time of our advice, you’d have $1,397,147!*
Now, it is value noting Inventory Advisor’s complete common return is 951% — a market-crushing outperformance in comparison with 214% for the S&P 500. Do not miss the newest high 10 checklist, accessible with Inventory Advisor, and be part of an investing neighborhood constructed by particular person traders for particular person traders.
*Inventory Advisor returns as of September 22, 2026.
Financial institution of America is an promoting companion of Motley Idiot Cash. Daniel Miller has no place in any of the shares talked about. The Motley Idiot has positions in and recommends Alphabet and Tesla. The Motley Idiot has a disclosure coverage.