Financial institution of America is sticking with its Purchase ranking on Meta Platforms (META) inventory after an early AI shock started altering how traders view the corporate’s tech spending.
That shock is Muse, Meta’s client AI assistant, launched on Sept. 8. The app can browse web sites, arrange e-mail, and full multi-step duties with restricted person intervention, pushing Meta past chatbots towards a sensible digital agent.
Early adoption has given the bull case momentum, whereas the sturdy preliminary numbers add weight to the argument that Meta may flip billions in AI infrastructure spending right into a differentiated client product.
Muse is starting to offer a solution, however it stays early. Nonetheless, it appears traders are catching on, with Meta inventory rising an incredible 36% over the previous month, dwarfing the broader market positive aspects of simply 1.2%, in accordance with Looking for Alpha information.
BofA however believes the launch has strengthened Meta’s AI trajectory and improved the case for its inventory.
BofA says Muse can reprice Meta’s AI story
Financial institution of America reiterated its Purchase ranking on Meta Platforms and set an $810 value goal. That represents 9.3% upside from the agency’s $741.25 reference value, though the potential return narrows to roughly 8% utilizing the Sept. 22 intraday value.
Extra AI:
In a BofA be aware shared with The Avenue, the corporate stated its new Muse providing would possibly lastly put to relaxation lots of the issues surrounding Meta if it will possibly ship a differentiated client product.
The early numbers look promising.
Citing Sensor Tower, BofA stated Muse surpassed 2.5 million cumulative U.S. downloads by Sept. 19 and reached roughly 557,000 day by day lively customers. Its 1.43 million iOS downloads by way of day 12 additionally edged ChatGPT’s 1.37 million on the similar stage.
Muse’s potential to execute multistep duties, together with managing e-mail, reserving journey, and finishing transactions, separates it from standard chatbots. Furthermore, Meta can ultimately promote the agent throughout its platforms, serving 3.6 billion day by day customers, creating a robust distribution benefit few opponents can match.
Unbiased testing discovered Muse genuinely helpful however probably uncomfortable as a result of private entry it requires.
That stated, strong retention may raise Meta’s valuation earlier than Muse contributes significant income, however downloads alone is not going to show lasting demand.
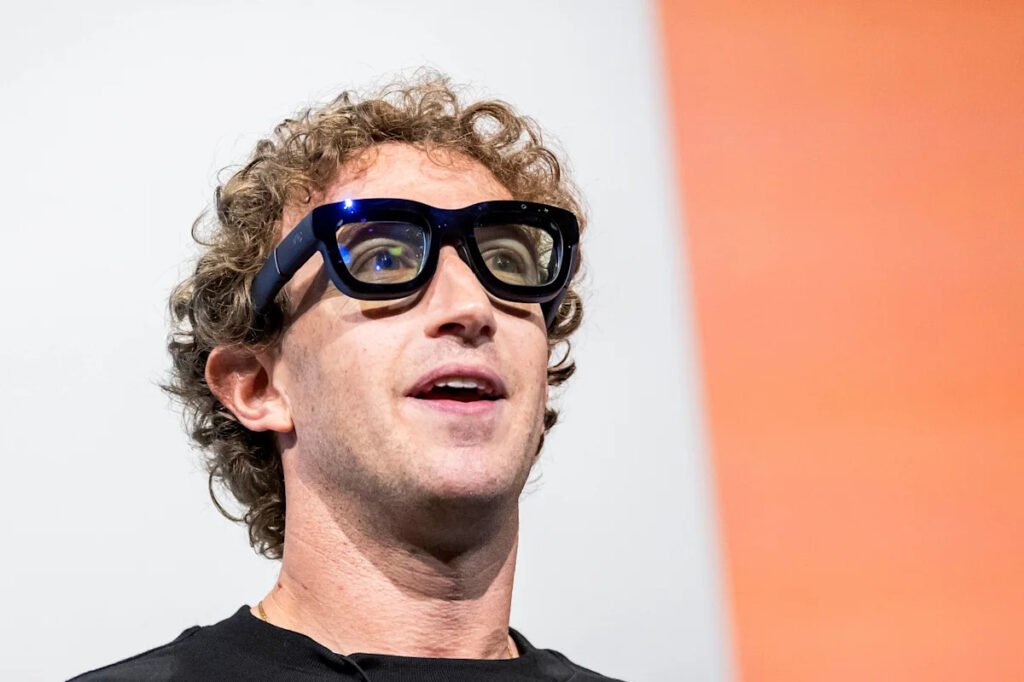
Financial institution of America backs Meta inventory as Muse positive aspects sturdy early traction.Bloomberg / Getty Pictures
Meta faces a multibillion-dollar compute determination
Muse additionally raises an vital query for Meta: Ought to it use its restricted AI computing energy for its personal merchandise or promote that capability to outdoors clients?
In its be aware, BofA estimates that exterior leasing may generate as much as $40 billion per gigawatt, primarily based on latest trade transactions. Leasing would create seen income and supply sooner proof that Meta’s infrastructure buildout can earn a suitable return.
Administration, nonetheless, believes client brokers and AI-enhanced promoting may in the end create larger worth.
Extra AI:
The stakes are large, to say the least. Meta expects 2026 capital expenditures of $130 billion to $145 billion, in contrast with $72.22 billion throughout 2025, Reuters famous. Each unit of compute is subsequently an opportunity-cost determination, not only a technical allocation.
Muse at the moment provides a free tier alongside $20 and $100 month-to-month subscriptions. BofA doesn’t anticipate subscriptions, promoting, or commerce commissions to develop into financially significant earlier than 2028.
On the flip aspect, Jefferies illustrated the longer-term alternative in a different way. Its situation assumes one billion customers by the tip of 2027 and three% paid conversion, producing $10.8 billion in annualized income.
Prioritizing Muse, subsequently, sacrifices probably profitable leasing revenue for a broader platform guess spanning subscriptions, commerce, APIs, and promoting.
Early engagement will assist decide whether or not that commerce pays off.
Investor takeaway: Meta’s execution should catch valuation setup
Meta inventory not carries the deep low cost that protected traders earlier within the yr. BofA stated shares commerce close to 21 occasions its 2027 earnings estimate, up from roughly 16 occasions a number of months in the past.
Its $810 goal applies a 24-times a number of to estimated 2027 GAAP earnings, representing a slight premium to the S&P 500. With solely about 8% upside from the intraday degree on Tuesday, Sept. 22, the margin for disappointment has narrowed significantly.
That makes Muse a supporting catalyst somewhat than a whole funding thesis. Traders have to see downloads translate into sturdy utilization, paid subscriptions, commerce exercise, or measurable promoting positive aspects earlier than pricing in additional a number of growth.
The dangers are interconnected.
Muse requires entry to delicate accounts, creating privateness and belief issues. Amazon has already blocked the agent from purchasing on its platform, demonstrating how third-party restrictions may weaken Muse’s usefulness and commerce ambitions.
In the meantime, Meta’s $130 billion to $145 billion spending plan pressures free money movement and raises the price of misjudging AI demand. Traders ought to monitor retention, paid conversion, task-processing prices, associate entry, and 2027 spending steering.
Muse has improved Meta’s AI narrative. At this valuation, nonetheless, it should develop into a monetizable behavior as an alternative of simply a powerful demonstration.